Burhan Sansarlioglu and Emir Yildirim
14 September 2026•Update: 14 September 2026
Global markets are trading on a mixed trend at the start of the week due to a decline in global risk appetite amid inflation concerns pushing bond yields higher, while reports that artificial intelligence (AI) firms may slow down development pressured tech stocks.
The US consumer price index (CPI) rose 0.4% on a monthly basis and 3.4% year-on-year in August, while core inflation defied estimates at 0.3% month-on-month.
All eyes turned to the Fed’s interest rate decision this week, with the probability of a rate hike rising to 87% in market estimates, following strong employment, rising inflation estimates and Fed Chair Kevin Warsh’s emphasis on price stability.
Meanwhile, rising oil prices continue to drive up bond yields and dampen risk appetite, and escalating geopolitical tensions in the Middle East contribute to these trends.
Saudi Arabia’s closure of the East-West Crude Oil Pipeline, or Petroline, due to attacks launched from Iraq intensified oil supply concerns. The pipeline boasts a daily capacity of 7 million barrels and was brought online as an alternative to the Strait of Hormuz.
November-delivery Brent crude oil is trading up 2.6% on Monday, reaching $107.3 a barrel.
The Strait of Hormuz meeting scheduled for Tuesday between Iran and Arab countries has been postponed.
The US 10-year Treasury yield tested its highest level since October 2023 at 4.98% and stabilized at 4.97%, while the US dollar is up 0.2% at 99.4, and gold is trading down 0.5% at $4,329 per ounce.
Meanwhile, AI development concerns came to the fore following a statement by Anthropic CEO Dario Amodei urging AI firms to slow down the pace of model development amid growing concerns over controlling AI systems.
Billionaire Elon Musk and OpenAI CEO Sam Altman expressed support for Amodei on their social media accounts.
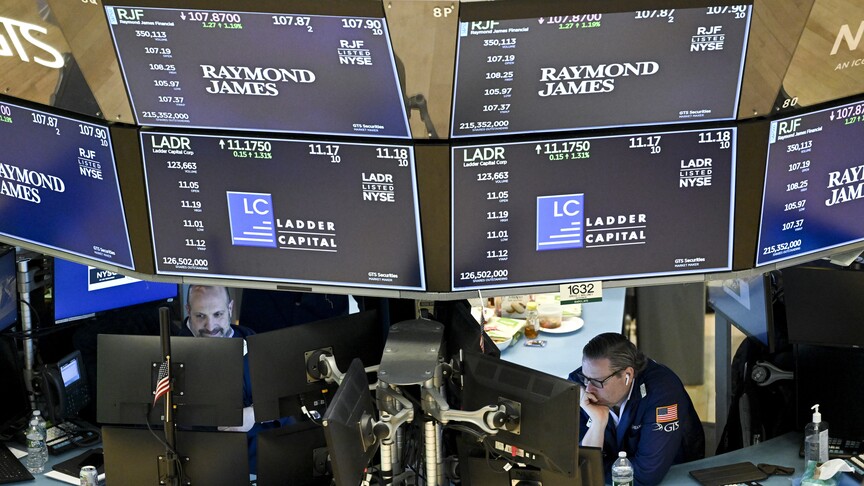
The New York Stock Exchange closed last week on a positive note as the rise in oil prices slowed amid reports of a potential agreement between Oman and Iran to temporarily regulate traffic through the Strait of Hormuz.
The University of Michigan’s consumer confidence index fell to 47.8 in September, below estimates, while short-term inflation expectations of consumers rose from 4% to 4.6% at the same time.
The US federal government’s budget posted a deficit of $167 billion in August, down 52% year-on-year.
The Dow Jones Industrial Average rose 0.98%, the S&P 500 gained 0.86%, and the Nasdaq was up 0.96% on Sept. 11. American indexes opened the new week on a negative trend.
Meanwhile, all eyes turned to the Bank of England’s (BoE) rate decision this week amid the buying-driven trend in European stock markets last week.
The BoE is expected to maintain its rates after the UK economy grew above estimates by 0.4% in July, while high energy costs continue to fuel inflationary pressures and keep bond yields high.
The UK's FTSE 100 rose 0.39%, Germany's DAX 40 gained 0.82%, France's CAC 40 increased 0.78%, and Italy's FTSE MIB 30 was up 1.36% on Sept. 11. European indexes opened Monday mixed.
Asian equity markets traded on a mixed trend near Monday’s close due to tech stock declines in the region.
Shares of South Korean tech firms SK Hynix and Samsung Electronics dropped 5.6% and 3.5%, respectively, while shares of Japan’s SoftBank Group fell 11.4%.
All eyes turned to the Bank of Japan’s (BoJ) interest rate meeting this week, when the bank is expected to raise its policy interest rate by 25 basis points from 1% amid rising energy costs and the yen’s depreciation.
Japan’s industrial production fell 0.2% on a monthly basis while rising 3.9% year-on-year, below estimates.
On a weekly basis, South Korea’s Kospi fell 2.8% and Japan’s Nikkei 225 dropped 1%, while Hong Kong’s Hang Seng climbed 0.4% and China’s Shanghai Composite was up 0.2%.