Burhan Sansarlioglu and Emir Yildirim
16 September 2026•Update: 16 September 2026
Global markets are trading on a mixed trend as the Fed is highly likely to hike rates for the first time in three years at its two-day meeting commencing on Wednesday.
Markets are anticipating a 25-basis-point rate hike due to strong US employment, rising inflation expectations and Fed Chair Kevin Warsh’s statements on price stability.
Warsh refrained from forward guidance, but his statements at the meeting will be monitored.
The US 10-Year Treasury yield rose to its highest since July 2007 at 5.04% on Tuesday and stabilized at 5% on Wednesday after Treasury Secretary Scott Bessent said the US bond market showed the world’s best performance.
Meanwhile, the US Senate failed to secure the necessary majority to move the Clarity Act bill to the floor for debate. The blocked act would have set a comprehensive regulatory framework for the crypto sector in the US.
Bitcoin dropped 0.1% to $75,780, while crypto exchange Coinbase’s shares dropped 10%.
November-delivery Brent crude dropped 0.6% to $108.1 a barrel despite concerns over geopolitical risks as US inventories rose, while gold was trading down 0.6% at $4,321 per ounce.
The US dollar was down 0.1% at 99.6 due to fiscal concerns despite rate hike expectations.
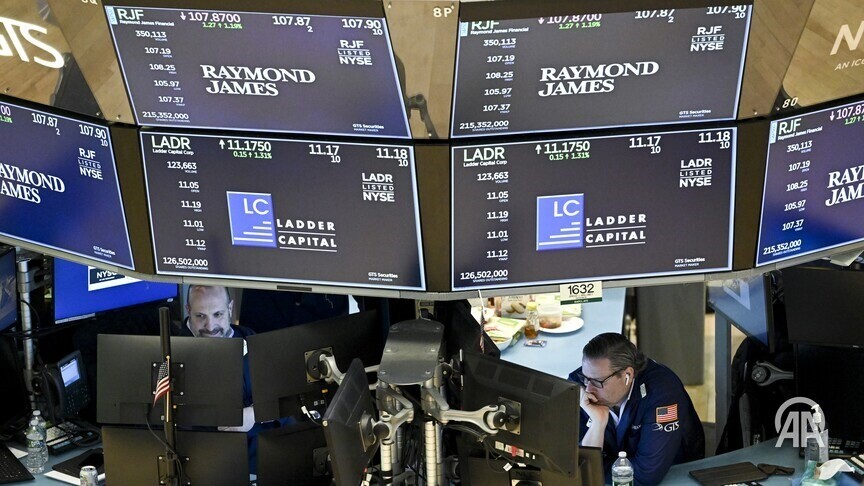
The New York Stock Exchange traded down on Tuesday due to rising bond yields dampening risk appetite.
Tech giant Meta’s stock gained nearly 1% after it said it started testing next-generation chips designed to run artificial intelligence (AI) models at lower costs and with less energy.
The New York Fed’s manufacturing index fell below estimates to 7.6 in September.
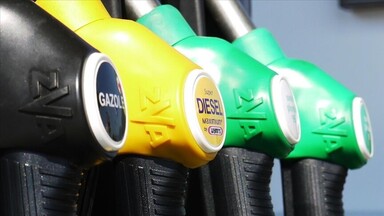
The average diesel price hit a new high of $6.27 a gallon, according to the American Automobile Association (AAA).
The Dow Jones Industrial Average fell 0.63%, the S&P 500 dropped 0.45% and the Nasdaq was down 0.78% on Tuesday. American indexes started Wednesday on a positive trend.
Meanwhile, European stock markets traded negatively on Tuesday due to rising oil prices and selling pressure in bond markets.
Germany’s ZEW Economic Sentiment Index rose from 34.2 in August to 34.7 in September, marking a modest increase but still coming in below the estimated level of 40. At the same time, Deutsche Bank shares dropped 2.4%.
The UK's FTSE 100 fell 0.37%, France's CAC 40 declined 0.34%, Italy's FTSE MIB 30 dropped 0.14% and Germany's DAX 40 closed Tuesday down 0.15%. European indexes started Wednesday on a mixed trend.
At the same time, Asian equity markets enjoyed boosted risk appetite amid slightly easing selling pressure in the bond market.
Japan’s exports rose 19.3% and imports surged 28% in August, above estimates.
Japan’s trade deficit grew for the fourth consecutive month, rising from 638.3 billion yen ($4.1 billion) to 1.1 trillion yen ($7.1 billion) amid rising energy costs.
Near Wednesday’s close, South Korea’s Kospi rose 0.3%, Hong Kong's Hang Seng grew 0.1%, China's Shanghai Composite increased 0.6% and Japan’s Nikkei 225 was up 0.3%.